At a glance
Real Shark Tank pitches in this guide
Swipe → Deal
Cousins Maine Lobster
Season 4 · Barbara Corcoran
 Deal
BeatBox Beverages
Season 6 · Mark Cuban
 Deal
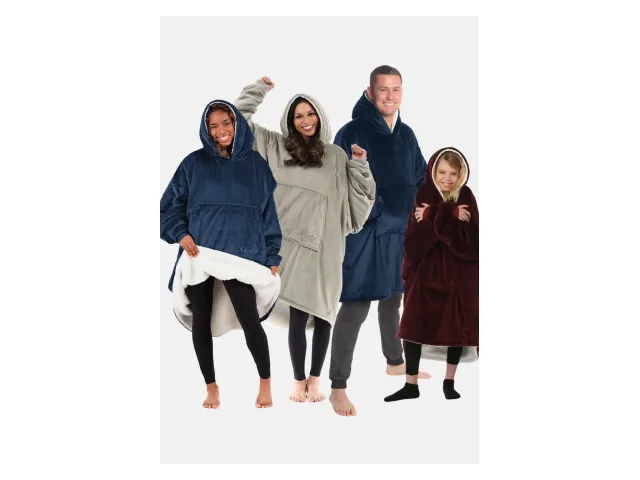
The Comfy
Season 9 · Barbara Corcoran
Deal
Hold Your Haunches
Season 5 · Barbara Corcoran
 Deal
Sweet Ballz
Season 5 · Barbara Corcoran
 Deal
Everlywell
Season 9 · Lori Greiner
Every Shark Tank pitch starts with a number that is really two numbers. When a founder says, "I'm seeking $100,000 for 10% of my company," they are stating both an investment amount and, implicitly, what they think the entire company is worth. Understanding that math is the first step to understanding why some pitches go smoothly and others stall the moment the ask is spoken.
This guide is educational and is not financial or legal advice. Real investments involve terms and risks that a qualified advisor should review.
The basic formula
The implied valuation is the investment divided by the equity percentage:
Valuation = Investment ÷ Equity %. For example, $100,000 ÷ 0.10 = $1,000,000.
A few more examples:
| Ask | Equity offered | Implied valuation |
|---|---|---|
| $50,000 | 20% | $250,000 |
| $100,000 | 10% | $1,000,000 |
| $250,000 | 5% | $5,000,000 |
| $500,000 | 10% | $5,000,000 |
| $1,000,000 | 4% | $25,000,000 |
You can run your own numbers in the valuation calculator.
Pre-money vs. post-money
Strictly speaking, the formula above gives the post-money valuation, the value of the company including the new cash. The pre-money valuation is the value before the investment:
- Post-money: $100,000 ÷ 10% = $1,000,000
- Pre-money: $1,000,000 − $100,000 = $900,000
On television this distinction is rarely spelled out, and people usually just say "a million-dollar valuation." In real term sheets the difference matters, so be clear which one you mean.
Why Sharks compare valuation to sales
Right after the ask, Sharks typically ask about sales. That's because they mentally divide the valuation by revenue to get a sales multiple.
Worked example: a founder asks $200,000 for 10%, a $2,000,000 valuation. The business did $400,000 in sales last year.
- $2,000,000 ÷ $400,000 = 5 times sales
Whether 5x is reasonable depends on margins, growth and category. A product company with thin margins and flat sales would generally be seen as expensive at 5x. A fast-growing brand with high margins and loyal repeat customers might justify more. Profit matters even more than revenue: if the same business earned $80,000 in profit, the valuation would be 25 times earnings, which most investors would consider rich for a small consumer company.
Why there's no "correct" multiple
Multiples vary by industry, growth rate, profitability, intellectual property and risk. The Sharks also weigh things that don't show up in a spreadsheet: how much work the deal will require from them, and how confident they are in the founder. That's why the same numbers can draw an offer from one Shark and a pass from another.
The classic counteroffer: same money, more equity
The most common Shark counteroffer keeps the dollar amount and raises the equity. Here's how that changes the valuation:
| Scenario | Investment | Equity | Valuation |
|---|---|---|---|
| Founder's ask | $100,000 | 10% | $1,000,000 |
| Counter A | $100,000 | 20% | $500,000 |
| Counter B | $100,000 | 25% | $400,000 |
| Counter C | $100,000 | 33.3% | $300,000 |
Doubling the equity from 10% to 20% halves the valuation. Founders who understand this can respond quickly and calmly, for instance by proposing a middle ground (15% implies about $667,000) or by changing the amount of money instead.
Other levers besides equity
- Less money for the same equity: $60,000 for 10% values the company at $600,000.
- Royalties: a payment per unit until the investor recoups their money (or more). See royalty deals explained.
- Loans or lines of credit: capital that's repaid with interest rather than exchanged for ownership.
- Contingencies: terms that depend on hitting milestones or completing a licensing deal.
- Multiple Sharks: two or more investors splitting the money and the equity. In our database, about 27% of on-air deals involved more than one Shark.
Our deal terms glossary defines all of these.
Real pitches to study
Our product pages list the deal outcome for each pitch. A few businesses worth studying for how valuation and partnership questions played out:
- Bombas (Season 6) closed a deal with Daymond John, a Shark known for apparel expertise.
- Cousins Maine Lobster (Season 4), a food truck and restaurant business, closed with Barbara Corcoran.
- BeatBox Beverages (Season 6), a wine-based party punch, closed with Mark Cuban.
- Everlywell (Season 9), an at-home lab test company, closed with Lori Greiner.
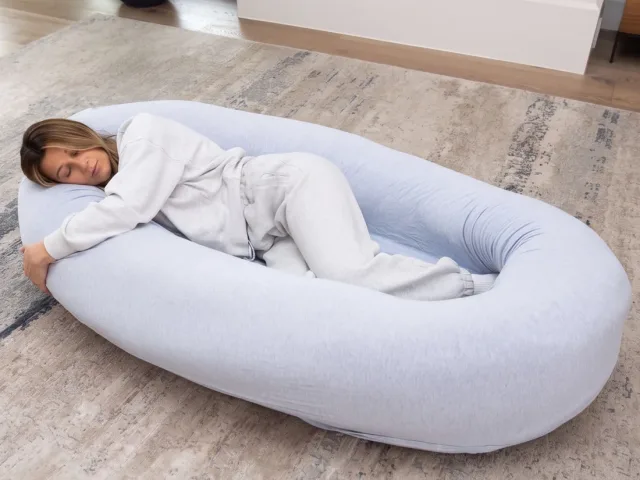
- The Comfy (Season 9), an oversized wearable blanket, closed with Barbara Corcoran.
- Sweet Ballz (Season 5) and Hold Your Haunches (Season 5) each closed with two Sharks, showing how investors sometimes team up and split a deal.
When you watch these episodes, track the ask, the implied valuation, the sales figures and the final terms. You'll start to see how often the final valuation moves away from the original ask.
A full walkthrough: from ask to handshake
Here's a hypothetical negotiation that shows how the numbers move. The company sells a kitchen gadget, did $300,000 in sales last year with a 55% gross margin, and is roughly break-even.
- The ask: $150,000 for 10%. Implied valuation: $1,500,000, or 5 times last year's sales.
- Shark A's offer: $150,000 for 30%. Implied valuation: $500,000, about 1.7 times sales. The Shark is saying the business is worth far less than the founder thinks.
- Shark B's offer: $150,000 for 15% plus a $1 per unit royalty until $150,000 is repaid. The equity implies a $1,000,000 valuation, but the royalty adds a cost the founder must model.
- Founder's counter to Shark A: $150,000 for 20%, a $750,000 valuation, citing a pending retail order.
- Possible landing point: $150,000 for 22.5%, about a $667,000 valuation.
Notice what happened: the founder's original 5x revenue valuation came down to a little over 2x. That's a common pattern on the show, and it's why preparing a defensible number matters so much. If the founder had opened at $150,000 for 15% ($1,000,000, or 3.3 times sales) with a clear explanation, the negotiation might have started from a more credible place.
Comparing offers on equal terms
When offers mix equity, royalties and loans, convert each to a rough picture of what the founder gives up over three to five years: the equity percentage, plus the total royalty payments at your expected sales volume, plus any interest. An offer with lower equity can still be the more expensive one once you add up the royalty dollars. Writing this comparison out before a negotiation, even for imaginary offers, makes it far easier to think clearly when the real ones arrive.
Why valuation isn't just about money
Founders sometimes accept a lower valuation from a Shark whose expertise fits their business. A Shark with retail and TV shopping experience, or one with deep apparel or food industry connections, may add value that cash alone can't buy. Others hold out for a higher valuation to preserve control. Neither choice is automatically right. What matters is understanding the trade-off you're making and choosing it deliberately.
What pushes valuation up or down
| Supports a higher valuation | Pushes valuation down |
|---|---|
| Strong, growing sales | Little or no revenue |
| High gross margins | Thin margins or high cost of goods |
| Repeat customers and subscriptions | One-time purchase with high ad costs |
| Issued patents or strong brand | Easy to copy |
| Profitable or near profitable | Heavy losses with no clear path |
| Full-time, experienced founder | Part-time founder, unclear commitment |
| Clean cap table | Heavy debt, existing investors with preferences |
How to set your own ask
- Start with how much money you actually need to reach a specific milestone.
- Decide how much ownership you're willing to give up. Many founders think in ranges, for example 10% to 25%.
- Divide to get the implied valuation and sanity-check it against your sales and profit.
- Look for comparable businesses in your category and stage.
- Decide your walk-away terms in advance so you aren't calculating under pressure.
For a fuller method, read How to Value Your Startup Before You Ask for Money. And remember that an on-air handshake is not a closed deal: terms can change during due diligence, as explained in what happens after Shark Tank.
Reminder: this article explains common concepts for education only and isn't financial, investment or legal advice.
Frequently asked questions
How do you calculate valuation on Shark Tank?
Divide the investment by the equity percentage. For example, $100,000 for 10% equals a $1,000,000 valuation. That figure is the post-money valuation; subtract the investment to get the pre-money valuation.
Why do Sharks ask for more equity than offered?
Sharks often think the founder's valuation is too high relative to sales or profit, or they want compensation for the risk and work involved. Asking for more equity for the same money lowers the valuation.
What is a sales multiple?
A sales multiple is the valuation divided by annual revenue. A $2 million valuation on $400,000 in sales is 5 times sales. Investors use it to compare a valuation against similar businesses.
Is a Shark Tank deal the same as the valuation in the ask?
Often not. Counteroffers frequently change the equity, the amount or the structure, and terms can also change during due diligence after taping.
Every pitch, deal and Shark mentioned here is checked against our database of 1,533 Shark Tank pitches. Cost ranges are typical estimates, not quotes. This is general education, not financial, legal or investment advice. Editorial policy · Suggest a correction
Keep learning
See all →
How to Value Your Startup Before You Ask for Money
Before you ask anyone for money, you need a defensible valuation. This guide walks through four…
Negotiation Lessons From the Tank
Shark Tank compresses a negotiation that normally takes weeks into minutes.
Shark Tank Deal Terms Glossary
A plain-English glossary of the deal terms you hear on Shark Tank, from equity and valuation to…
Shark Tank Royalty Deals Explained
A royalty deal pays the investor a fixed amount or percentage on every unit sold, often until they…
Know Your Numbers: The Metrics Sharks Grill Founders On
Sharks judge a business by a handful of numbers: sales, margins, landed cost, customer acquisition…
Which Shark Should You Pitch? Each Shark's Investing Style
Each Shark brings a different background, investing style and set of favorite categories.
How to Start a Snack Brand: Lessons From 10 Shark Tank Pitches
Snacks are one of the most crowded aisles in the grocery store and one of the most frequently…
How to Start a Pet Services Business: Lessons From 8 Shark Tank Pitches
Grooming, daycare, training and specialty pet services turn love of animals into recurring local…
How to Start a Sneaker & Footwear Brand: Lessons From 12 Shark Tank Pitches
Footwear is one of the hardest fashion categories to launch, with high minimums and endless sizes…